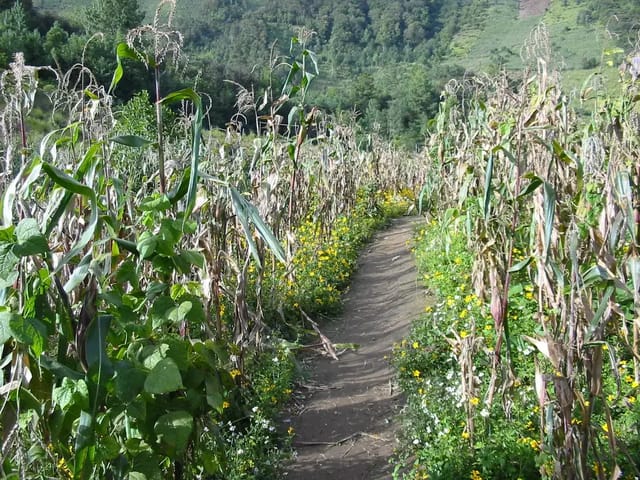
Two grains carry the Guatemalan table: maíz blanco (white corn, for tortillas) and frijol negro (black beans). Their price is one of the most direct, daily-felt economic indicators in the country — and in 2026 it sits at the intersection of a failed harvest, depleted reserves, and a newly declared El Niño.
In MAGA’s weekly report for 26-30 October 2026, first-quality white corn averaged Q200.00 per quintal wholesale and black beans Q625.00 per quintal at La Terminal in Guatemala City; on 22 June 2026 they were Q195.00 and Q525.00. Those are the headline numbers. The story behind them is why they matter, where they’re headed, and who feels them first.
This page lays out the current 2026 wholesale prices, the primera/postrera harvest mechanics that govern them, the El Niño drought risk hanging over the next harvest, and how grain prices flow into the canasta básica and the millions of households who buy their staples at market.
Quick summary: In MAGA’s weekly report for 26-30 October 2026 (La Terminal wholesale), maíz blanco de primera averaged Q200/quintal and frijol negro Q625/quintal; MAGA’s October 2026 averages were Q219.88 for white corn (6.58% above October 2025) and Q635.00 for black beans (1.60% above October 2025). FEWS NET projects maize prices roughly 10-15% above the five-year average through the Feb-Sep 2026 outlook, while bean prices stay near average. The 2025 Dry Corridor harvests failed badly — poorest households lost more than 70% of maize and almost all beans in the primera cycle — leaving reserves below normal. The lean season peaks June-August, with FEWS NET estimating the population in need of food assistance at 2.0-2.4 million between June and August. NOAA’s El Niño Advisory (held since 11 June 2026; the 8 October 2026 discussion puts Niño-3.4 at +2.1°C and calls a strong-to-very strong El Niño likely through January-March 2027, greater than an 83% chance) now threatens the postrera (Nov-Dec) harvest — the core forward risk for prices into early 2027.
Explore the data: The Guatemala Weather Hub shows live rainfall accumulation for 22 departments versus the 30-year normal, plus the current ENSO state pulled from NOAA. Because corredor seco harvest failures start as rainfall deficits, the Weather Hub is the earliest leading indicator of the drought pressure that ultimately shows up in grain prices. For the food-cost side, the Guatemala food basket page tracks the official INE canasta básica.
Latest Wholesale Prices (MAGA, 26-30 October 2026)
MAGA’s weekly report for La Terminal, zona 4, Guatemala City, for 26-30 October 2026:
| Grain | Weekly average (Q / quintal) | Change on the week | October 2026 average | vs October 2025 |
|---|---|---|---|---|
| White corn, first quality | 200.00 | +5.26% (Q10.00) | Q219.88 | +6.58% |
| Black beans | 625.00 | -2.60% (Q16.67) | Q635.00 | +1.60% |
Source: MAGA, Informe semanal de precios al mayorista, 26-30 October 2026. MAGA links the corn rise to limited national grain after crop losses, especially in the east, partly offset by Mexican corn; it links the bean drop to imported grain adding supply.
Earlier Snapshot: Daily Wholesale Prices (MAGA, 22 June 2026)
These are wholesale prices (al mayorista) per quintal — a quintal is 100 pounds — quoted at La Terminal, the central wholesale market in zona 4 of Guatemala City. They are MAGA’s official daily figures for 22 June 2026, kept here for comparison with the October figures above.
| Grain | Quality | Wholesale price (Q / quintal) |
|---|---|---|
| White corn (maíz blanco) | First quality | 195.00 |
| White corn (maíz blanco) | First quality, other origins | 190.00 |
| White corn (maíz blanco) | Second quality | 185.00 |
| Black beans (frijol negro) | First quality | 525.00 |
| Black beans (frijol negro) | Second quality | 500.00 |
Source: MAGA Sistema de Información de Mercados, daily wholesale prices, 22 June 2026.
A few notes on reading these:
- Quintal vs pound vs market price. These are wholesale per-quintal figures. The price a family actually pays per pound at a neighborhood tienda is higher than the per-quintal wholesale rate divided by 100 — there’s a retail margin on top. We do not publish a per-pound retail figure here because the source MAGA daily sheet we used reports wholesale per quintal, not retail per pound.
- First vs second quality. MAGA lists a first-quality (de primera) and a second-quality grade; the second is the lower one and, in the June table, second quality was Q10 to Q25 cheaper per quintal. Both are real, traded grades.
- The beans-to-corn ratio. Black beans cost about 2.7 times what corn does per quintal — Q525 vs Q195 for first quality on this date. Beans are more expensive to grow, more sensitive to weather, and store differently, which is why the two staples don’t move in lockstep.
For the live, current-day version of these prices, MAGA’s portal at precios.maga.gob.gt is the primary source.
Prices vs the Five-Year Average
A single day’s price doesn’t tell you whether grain is expensive or cheap by Guatemalan standards. For that you need the trend, and the clearest trend data comes from FEWS NET (the Famine Early Warning Systems Network), which tracks Guatemalan staple-grain markets against their five-year average.
| Measure | 2026 level vs five-year average | Source |
|---|---|---|
| Maize (wholesale) | Roughly 10-15% above | FEWS NET, February 2026 outlook |
| Black beans | Near average / stable | FEWS NET, February / May 2026 |
| Decline from mid-2024 peak (as of January 2026) | Maize −35%, beans −18% | FEWS NET, February 2026 outlook |
Sources: FEWS NET Guatemala Food Security Outlook, February 2026; FEWS NET Global Price Watch, May 2026.
Three things stand out:
One — corn is elevated, beans are not. FEWS NET’s February 2026 outlook projects maize wholesale prices staying 10-15% above the five-year average through the February-September 2026 period, while bean prices are expected to remain near their five-year average. The May 2026 Price Watch confirmed the split: staple grains were “close to average in Guatemala, supported by above-average imports,” with black bean prices near average and red bean prices above average.
Two — prices already came down from a 2024 high. The mid-2024 period was a price peak. By January 2026, maize prices had fallen about 35% and bean prices about 18% from those 2024 peaks (FEWS NET, February 2026). Notably, prices “remained atypically high through the end of the year despite the arrival of fresh grain” before stabilizing in January 2026. So 2026 is starting from a calmer level than 2024 — but on top of weak reserves, which is the catch. (We don’t publish the exact 2024 peak quetzal figure: FEWS NET reports only the percentage decline, not the peak price, so there’s no sourced quetzal value to quote.)
Three — imports are doing the cushioning. The reason staples are “close to average” rather than spiking is that above-average imports are holding supply up. That’s a structurally important detail: the domestic harvest situation is worse than the price alone suggests, and imports are absorbing the gap. If that import cushion thins — or if a failed postrera deepens the domestic shortfall — the price floor is less protected than it looks.
The earlier October 2025 outlook had framed staple grains as 5-15% above the five-year average through 2026, with beans elevated “due to low production over the last three years from weather impacts.” The February 2026 numbers refine that picture: corn stayed elevated, beans pulled back to near average.
The Harvest Cycle Behind the Price
To understand grain prices in Guatemala you have to understand the two-cycle rainfed calendar. Almost everything about timing and risk flows from it.
| Cycle | Planting | Harvest |
|---|---|---|
| Primera | February-April | May-September |
| Postrera | June-August | November-December |
| Lean season | Peaks June-August | (between harvests) |
Source: FEWS NET Guatemala Food Security Outlook, February 2026.
The primera is the main cycle, planted with the first rains in February-April and harvested May-September. The postrera is the second cycle, planted June-August and harvested November-December. Between the two harvests sits the lean season, which peaks June-August — exactly the period this page is being published in. During the lean season, household grain stocks from the previous harvest are running out, the next harvest isn’t in yet, and families depend most heavily on buying from the market. That’s when prices have the most leverage over hunger.
This calendar is also why the canícula — the mid-season dry spell that INSIVUMEH places in July and part of August — is so dangerous. It hits during the most water-sensitive growth stage of the primera corn crop, and in a strong El Niño year it can stretch and intensify. (See Canícula Guatemala 2026 for the full mechanism.)
What 2025 Did to the Reserves
The reason 2026 is fragile despite calmer prices is that 2025 was a bad crop year in the Dry Corridor, and the damage carried forward.
FEWS NET’s reporting is blunt about it:
- In the 2025 primera cycle, the poorest Dry Corridor households lost more than 70% of their maize harvests and almost all of their bean harvests, and the harvest was delayed from August-September into late September/October (FEWS NET, October 2025).
- Subsistence farmers in the Dry Corridor reported “almost total losses of maize and total losses of beans” from 2025 weather impacts, leaving grain reserves “substantially below normal” (FEWS NET, February 2026).
- Prolonged dry spells and high temperatures delayed primera planting by up to 40 days in some Dry Corridor areas during the October 2025-May 2026 window (FEWS NET, November 2025).
- “Many poor households suffered near-total maize and bean losses during both the 2025 primera (April-September) and postrera (September-November) seasons” (FEWS NET, November 2025).
The phrase that matters most is “substantially below normal” reserves. A family or a region that goes into a new year with full granaries can ride out a bad market. One that starts empty has no buffer — every shortfall translates straight into market dependence and, ultimately, food insecurity. That’s the condition Guatemala’s poorest grain-growing households are in for 2026.
The corredor seco — Zacapa, Chiquimula, Jutiapa, El Progreso, plus parts of Baja Verapaz, Jalapa, Santa Rosa, and Quiché — is the region INSIVUMEH’s 2018 climate study records as the driest in the country (Valles del Oriente, 700 to 1,300 mm a year). That thin margin is why El Niño rainfall deficits translate so quickly into primera and postrera failures there, and why the region is the structural epicenter of Guatemala’s grain-price and food-security story.
The El Niño Risk Over the Next Harvest
This is the forward-looking core of the page. The current prices are calm-ish; the risk is what happens to the next harvest.
NOAA’s Climate Prediction Center upgraded its May El Niño Watch to a full El Niño Advisory on 11 June 2026, and the Advisory has been in place ever since. The current reading is the 8 October 2026 ENSO Diagnostic Discussion, which has El Niño strengthening further: the Niño-3.4 index at +2.1°C, Niño-3 at +3.0°C and the coastal Niño-1+2 region at +3.9°C, with sea-surface temperature anomalies exceeding +4.0°C in portions of the eastern equatorial Pacific. NOAA calls a strong-to-very strong El Niño likely through January-March 2027 (greater than an 83% chance) and raises to 83% the chance of a historic event during October-December 2026 (75% in September) — defined as a three-month RONI value of +2.5°C or more, which would exceed every El Niño back to 1950. For the trajectory: on 11 June the weekly Niño-3.4 anomaly was +0.7°C with Niño-1+2 at +2.1°C and a 63% very-strong probability for November-January; the 9 July issue read +1.2°C and 81%; the 13 August issue read +1.4°C for July, with Niño-3 at +1.7°C, Niño-1+2 at +2.9°C, and a 69% historic-event probability; the 10 September issue read +1.8°C for August, with Niño-4 at +0.1°C and a greater than 90% chance of a very strong El Niño for Northern Hemisphere fall and winter. The next update is 12 November 2026. (Full detail: El Niño Guatemala 2026.)
Here’s why that lands directly on grain prices:
- The postrera harvest (November-December) falls right as El Niño is forecast to be strengthening toward its very-strong peak. A drought-stressed postrera would fail on top of already-depleted reserves.
- Historically, the major El Niño drought years in Guatemala — 1982-83, 1997-98, 2014-2016, 2015-16, 2018-2019 — produced serious corredor seco harvest losses. A very-strong event is, by NOAA’s framing, the kind that tilts the odds most heavily toward that outcome.
- The mechanism that turns drought into price is the same one described above: failed local harvests → more market dependence → tighter domestic supply → upward price pressure, especially if the import cushion doesn’t expand to match.
The thesis, stated plainly: a failed postrera in a very-strong El Niño year, landing on substantially-below-normal reserves, is the scenario that would re-tighten Guatemala’s grain supply and pressure maíz and frijol prices into early 2027. It is not a forecast of a specific price. It’s the risk structure the current calm sits on top of, and the next data point that will move it is the 8 October 2026 NOAA update.
Food Security: Who Feels It First
Grain prices in Guatemala aren’t an abstraction — they map onto a measurable food-security crisis. The people who feel a Q10 move in the price of a quintal of corn are the same people FEWS NET and the IPC are counting.
| Metric | Value | Period |
|---|---|---|
| People needing food assistance | 2.0-2.4 million | June-August 2026 |
| People in IPC Phase 3+ (Crisis or worse) | ~3 million (about 1 in 6) | February-April 2026 |
| Maize harvest loss (Dry Corridor, 2025 primera) | More than 70% | 2025 primera cycle |
Sources: FEWS NET Guatemala Food Security Outlook, February 2026 and October 2025.
FEWS NET’s February 2026 outlook estimated the population in need of food assistance at 2.0-2.4 million between June and August 2026, the lean season — up from a 1.5-1.99 million estimate for the October 2025-May 2026 window. IPC analysis projected about 3 million people, roughly 1 in 6 Guatemalans, facing IPC Phase 3 (Crisis) or worse during February-April 2026, with Crisis-level outcomes projected February-September 2026 for the poorest households in the Dry Corridor, southern Alta Verapaz, and the Western Highlands; much of the rest of the country was Stressed (IPC Phase 2) in February.
FEWS NET attributes the severity to “an early lean season … prolonged dependence on markets, above-average food and transportation prices, and a seasonal decline in rural incomes.” In other words, the price of grain is not a side effect — it’s one of the named drivers of the crisis.
How Grain Prices Flow Into the Canasta Básica
The bridge from wholesale grain prices to what families actually spend is the canasta básica alimentaria (CBA), the official basic food basket measured monthly by INE.
| Area | CBA per person / month (Q) | ~USD | Change vs April | Products |
|---|---|---|---|---|
| Urban | 941.86 | ~121 | +0.57% | 66 |
| Rural | 726.00 | ~93 | +0.55% | 60 |
Source: INE canasta básica alimentaria, May 2026 (reported 15 June 2026). Primary INE portal: ine.gob.gt.
In May 2026, INE put the per-person monthly food basket at Q941.86 urban and Q726.00 rural, both up about half a percent versus April. The urban basket covers 66 products and the rural basket 60 (the current product lists have been in force since January 2024). Within the rural basket, the basic-grains group accounts for Q31.64 per person per month — alongside Q134.51 for bread and cereals and Q114.57 for meat, poultry, fish and eggs.
That Q31.64 line is the direct grain-price exposure: it’s the part of the rural food budget that moves when maíz and frijol move. Because tortillas and beans are eaten at essentially every meal, a grain-price increase doesn’t stay contained to one line — it’s the most-purchased, least-substitutable part of the basket. For a deeper monthly breakdown, see the Guatemala food basket page.
There’s a remittance dimension here too. Many Guatemalan households, especially in the Dry Corridor, depend on money sent home by relatives in the United States, and in bad harvest years that income is often the real buffer that lets families keep buying staples at market prices. When local grain fails, remittance-funded households absorb the higher market cost rather than eating their own harvest. (We keep this point qualitative — there’s no sourced remittance-dollar figure on this page.)
What to Watch Through 2026-27
The price of corn and beans in Guatemala over the next twelve months hinges on a short list of dated signals:
10 September 2026— happened. The very-strong probability held at greater than 90%, and the October-December historic-event probability rose from 69% to 75%, with August’s Niño-3.4 at +1.8°C.8 October 2026— happened. The October-December historic-event probability rose from 75% to 83%, with Niño-3.4 at +2.1°C, and NOAA’s strength wording became a strong-to-very strong El Niño likely through January-March 2027 (greater than an 83% chance).- 12 November 2026 — the next NOAA ENSO Diagnostic Discussion. NOAA issues these on the second Thursday of each month. Watch whether the 83% October-December and 70% November-January historic-event probabilities hold. A stronger El Niño raises the postrera-failure risk.
- July-August 2026 — the canícula and the lean-season peak together. This is the first ground-truth window: an extended canícula across multiple corredor seco departments would signal real drought pressure on the pending primera harvest.
- May-September 2026 — the primera harvest comes in. A weak primera keeps reserves thin heading into the postrera planting.
- November-December 2026 — the postrera harvest, the one most exposed to a strengthening El Niño. This is the pivotal harvest for prices into early 2027.
- Daily — MAGA wholesale prices at precios.maga.gob.gt and the Weather Hub rainfall tracker, the two fastest-moving indicators.
Practical Takeaways
For households and budgeters. First-quality white corn averaged Q200/quintal and black beans Q625/quintal wholesale in MAGA’s 26-30 October 2026 report. FEWS NET’s February outlook expected maize 10-15% above its five-year average and beans near average. The forward risk is a failed postrera harvest tightening supply into early 2027.
For anyone tracking the canasta básica. Grain is a small but unavoidable line of the food basket (Q31.64/person/month of basic grains in the rural basket). Watch the monthly INE release for the food-cost trend; watch MAGA for the daily grain trend.
For travelers and researchers. Guatemala’s grain-price story is one of the clearest economic windows into how El Niño climate risk converts into food cost and food insecurity. The corredor seco is where it concentrates, the lean season (June-August) is when it bites, and the postrera harvest is the next major test.
The bottom line: 2026 is starting from relatively calm grain prices held up by imports, sitting on top of depleted reserves, with a declared, possibly very-strong El Niño threatening the next harvest. That’s a stable surface over an unstable foundation — and the data to watch it move is published daily.
Related Reading
- El Niño Guatemala 2026 — the full NOAA Advisory, the October 8 strength forecast, and what El Niño does to Guatemala’s rain, drought, and hurricanes.
- Canícula Guatemala 2026 — the mid-season dry spell that hits corn at its most vulnerable growth stage, and how El Niño can stretch it.
- Drought in Guatemala 2026 — the El Niño drought risk driving the price pressure, and where it bites hardest.
- Guatemala’s Corredor Seco — the dry-corridor smallholders whose crop losses move the staple-grain market.
- Guatemala Rainy Season 2026 — the invierno calendar that the primera and postrera cycles are built around.
- Hurricane Season Guatemala 2026 — the flip side of El Niño: suppressed Atlantic activity, and what that means for Caribbean-side rainfall.
- Guatemala Food Basket Cost — the official INE canasta básica alimentaria, updated monthly, where grain prices land in the household budget.
- Guatemala Weather Hub — live ENSO state from NOAA and rainfall accumulation vs the 30-year normal for 22 departments — the earliest leading indicator of drought pressure on grain.
Sources
- MAGA — Informe semanal de precios al mayorista (La Terminal), 26-30 October 2026: precios.maga.gob.gt
- MAGA — Sistema de Información de Mercados, daily wholesale prices (La Terminal), 22 June 2026: precios.maga.gob.gt/diarios/diarios.html and the portal precios.maga.gob.gt.
- FEWS NET — Guatemala Food Security Outlook, February 2026: fews.net.
- FEWS NET — Guatemala Food Security Outlook, October 2025: fews.net.
- FEWS NET — Analysis Note, Impacts of Dry Conditions (November 2025): fews.net.
- FEWS NET — Global Price Watch, May 2026: fews.net.
- Guatemala’s export crop, priced the same way: live coffee prices — the ICE “C” contract and the ICO Other Milds indicator, per quintal as well as per pound.
- INE — Canasta Básica Alimentaria (portal): ine.gob.gt; May 2026 figures reported via Infobae, 15 June 2026.
- NOAA Climate Prediction Center — ENSO Diagnostic Discussion, 8 October 2026 (El Niño Advisory; Niño-3.4 +2.1°C, Niño-3 +3.0°C, Niño-1+2 +3.9°C; strong-to-very strong likely through January-March 2027, greater than 83%; 83% historic Oct-Dec; next discussion 12 November 2026): cpc.ncep.noaa.gov, read at the source on 15 October 2026 (UTC). Prior issues: 10 September 2026 (read at the source on 21 September 2026), 13 August 2026, 9 July 2026, 11 June 2026.
Frequently Asked Questions
What is the price of corn in Guatemala in 2026?
MAGA’s weekly wholesale report for La Terminal in Guatemala City puts first-quality white corn (maíz blanco de primera) at an average of Q200.00 per quintal (100 lb) for 26-30 October 2026, up 5.26% on the week; MAGA links the rise to limited national grain after crop losses, especially in the east. On 22 June 2026 MAGA’s daily system had it at Q195.00. Other-origin first-quality corn was Q190.00 and second-quality corn Q185.00 per quintal. These are wholesale (al mayorista) prices and change daily. FEWS NET projects maize wholesale prices will stay roughly 10-15% above the five-year average through the February-September 2026 outlook period.
What is the price of black beans in Guatemala in 2026?
MAGA’s weekly wholesale report for La Terminal puts black beans (frijol negro) at an average of Q625.00 per quintal for 26-30 October 2026, down 2.60% on the week as imported grain added supply. On 22 June 2026 MAGA’s daily system had first quality at Q525.00 and second quality at Q500.00. Unlike corn, FEWS NET expects bean prices to remain near their five-year average in 2026 — black bean prices were described as near average in the May 2026 Price Watch, while red bean prices ran above average.
Why are staple grain prices high in Guatemala in 2026?
Three things stack up. First, the 2025 Dry Corridor harvests failed badly — poorest households lost more than 70% of their maize harvest and almost all of their bean harvest in the 2025 primera cycle (FEWS NET), leaving grain reserves substantially below normal going into 2026. Second, the lean season peaks June-August, when households depend most on the market and the next harvest is still pending. Third, NOAA has held an El Niño Advisory since 11 June 2026, and its 8 October 2026 discussion has El Niño strengthening further — the Niño-3.4 index at +2.1°C and a strong-to-very strong El Niño likely through January-March 2027 (greater than an 83% chance); the 10 September discussion had given a greater than 90% chance of a very strong event during Northern Hemisphere fall and winter 2026-27 (on 11 June the index was +0.7°C and the very-strong probability 63%). That threatens the postrera (November-December) harvest. Above-average imports are currently cushioning supply and keeping staples close to average.
How much does El Niño affect corn and bean prices?
El Niño’s effect is indirect but real: it drives the rainfall deficits and extended canícula that cause primera and postrera harvest failures in the corredor seco (Zacapa, Chiquimula, Jutiapa, El Progreso and surrounding areas), which INSIVUMEH’s 2018 climate study records as the driest region in the country (Valles del Oriente, 700 to 1,300 mm a year). When local harvests fail, households buy more from the market, and domestic supply tightens. The core forward risk for 2026 is a failed postrera (November-December) harvest landing on top of already-depleted reserves — that combination would re-tighten supply and pressure prices into early 2027.
What is the primera and postrera harvest cycle?
Guatemala grows staple grains in two main rainfed cycles. The primera cycle is planted February-April and harvested May-September. The postrera cycle is planted June-August and harvested November-December. The lean season — when household stocks run lowest and prices are most exposed — peaks June-August, between the two harvests. (Source: FEWS NET Guatemala Food Security Outlook, February 2026.)
How does corn and bean cost relate to the canasta básica?
Staple grains are a core component of Guatemala’s canasta básica alimentaria (basic food basket). In May 2026, INE put the per-person monthly food basket at Q941.86 in urban areas and Q726.00 in rural areas. The basic-grains group accounted for Q31.64 per person per month in the rural basket. Because maíz and frijol are eaten daily, even modest grain-price moves feed directly into household food costs — and into the remittance-funded households that buy staples at market prices.
How many people in Guatemala need food assistance in 2026?
FEWS NET’s February 2026 outlook estimated that the population in need of food assistance would reach between 2.0-2.4 million between June and August 2026. Separately, IPC analysis projected about 3 million people — roughly 1 in 6 Guatemalans — to face IPC Phase 3 (Crisis) or worse during February-April 2026, with Crisis-level outcomes projected February-September 2026 for the poorest households in the Dry Corridor, southern Alta Verapaz, and the Western Highlands.
Where can I check current Guatemala grain prices myself?
MAGA (Guatemala’s Ministry of Agriculture) publishes daily wholesale prices through its Sistema de Información de Mercados at precios.maga.gob.gt. The daily market sheet at precios.maga.gob.gt/diarios/diarios.html lists per-quintal wholesale prices for maíz blanco, frijol negro and other products at La Terminal. For the basic food basket, INE publishes the canasta básica alimentaria monthly at ine.gob.gt.